Business Migration to Malaysia: 7 Steps for ASEAN Growth
Business migration to Malaysia is not simply a decision to incorporate a company in another country. For a founder or investor with international ambitions, it can involve deciding where the business operates, where management decisions are made, how funds move, which immigration route applies and how the family will establish a practical life alongside the business.
A registration certificate on its own does not create a workable regional base. The stronger approach aligns corporate structure, immigration, banking, tax coordination and day-to-day operations before major commitments are made.
For founders looking towards ASEAN, Malaysia can form part of a broader regional strategy. The appropriate structure, however, depends on what the business actually does, where its customers and suppliers are located, where its people work and whether the founder intends to live and work in Malaysia.
Why Malaysia Can Be an ASEAN Operating Base
Malaysia occupies a useful position within Southeast Asia, with established infrastructure, international business connections and access to major ASEAN markets.
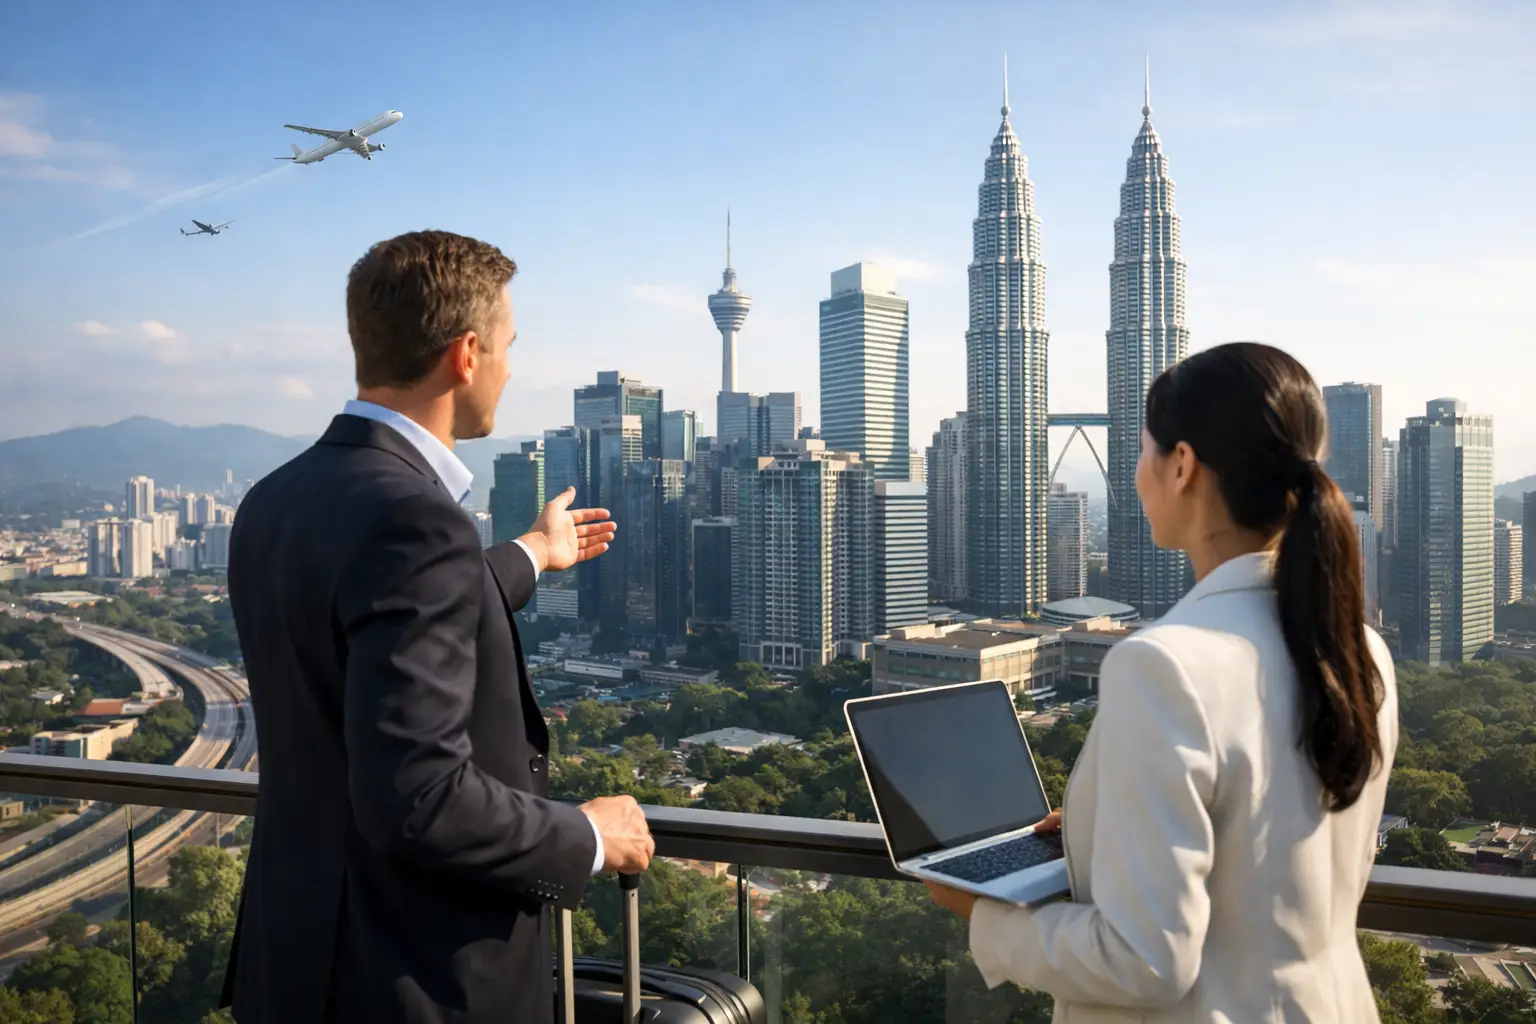
Kuala Lumpur also provides many of the practical features internationally mobile founders may need, including professional services, international education, private healthcare, air connections and a sizeable expatriate community.
The opportunity is not limited to one type of business. Consulting firms, technology companies, e-commerce businesses, trading operations, regional service providers and other internationally focused businesses may consider Malaysia as part of their expansion strategy.
But location alone does not make a business model successful. The important question is how Malaysia fits into the company’s actual commercial plan.
7 Steps for Business Migration to Malaysia
1. Define the Role Malaysia Will Play in the Business
The first question should not be, “Which company is cheapest to form?”
Instead, ask:
- Will Malaysia become the company’s main operating base?
- Will the business employ people in Malaysia?
- Will it contract directly with Malaysian customers?
- Will the founder manage the company from Malaysia?
- Will Malaysia support expansion into other ASEAN markets?
- Which activities will remain outside Malaysia?
A company serving international customers from Malaysia may have different requirements from a company selling directly into the Malaysian domestic market.
Likewise, a founder who wants to live in Kuala Lumpur while managing an international business may need a different corporate and immigration plan from an entrepreneur establishing a local trading operation.
Defining the role of Malaysia first prevents the corporate structure from being selected in isolation.
2. Choose the Corporate Structure Around Real Operations
A Malaysian private limited company can be appropriate when the business will employ local staff, contract with Malaysian customers, maintain premises, trade locally or build a substantial domestic operation.
SSM’s current incorporation guidance states that a Malaysian private company must have at least one director who ordinarily resides in Malaysia. It also sets out the incorporation requirements and procedures under the Companies Act 2016. See SSM’s official company-incorporation guidance.
Labuan can be relevant for qualifying international business activities and cross-border structures. Labuan FSA states that incorporation is undertaken through a licensed Labuan trust company and that the appropriate regulatory and substance requirements apply. See Labuan FSA’s Labuan Companies guidance.
The two structures should not be treated as interchangeable.
A Malaysian operating company may be more appropriate where local commercial activity is central to the business. A Labuan structure may be relevant where the business genuinely falls within the applicable Labuan framework.
For some businesses, a combination of entities may also be considered. The appropriate structure depends on the actual commercial model, ownership, customers, management, employees and regulatory requirements.
3. Review Tax and Substance Before Incorporation
Cross-border tax planning should begin before the company is established, not after money starts moving between countries.
Founders relocating from another jurisdiction may need to consider personal tax residence, corporate tax exposure, management and control, beneficial ownership, related-party transactions and continuing obligations in their previous country.
Malaysia can form part of an efficient international structure, but there is no universal tax outcome. The result depends on the company’s activities, contractual arrangements, management, ownership and the jurisdictions connected to the business and its founders.
For Labuan structures, substance and the nature of the business activity are particularly important. A registered address by itself should not be treated as a substitute for the applicable operational requirements.
Our Labuan Economic Substance Requirements guide explains why employees, operating expenditure, decision-making and actual business activity need to be considered together.
The key principle is simple: the structure should reflect commercial reality rather than being created solely around a headline tax proposition.
4. Build Immigration Into the Business Migration Plan
A founder should not assume that owning or incorporating a Malaysian company automatically provides the right to live and work in Malaysia.
Company incorporation and immigration permission are separate matters. The appropriate immigration route depends on the founder’s circumstances, role, employing entity and applicable Malaysian requirements.
For businesses employing eligible expatriates, Malaysia’s Expatriate Services Division is the relevant government platform for company registration and expatriate-related applications. ESD states that companies need to register with ESD before applying for relevant expatriate passes. See the official ESD company-registration guidance.
For an owner who intends to actively work in Malaysia, the immigration strategy should therefore be considered alongside the corporate setup.
Questions to resolve early include:
- Who owns the company?
- Who will act as director?
- Who will perform the day-to-day role?
- Which entity will employ the founder where employment is required?
- What business activities will the founder actually perform?
- Which family members require dependent or related immigration arrangements?
Malaysia’s current Employment Pass framework also ties the pass to the employing organisation. The official ESD guidance should be checked before relying on any specific immigration route or eligibility assumption. See current Employment Pass information from ESD.
5. Prepare Banking Before the Business Moves
Banking is often where otherwise sound international business plans encounter practical questions.
Financial institutions can assess the people behind the company, source of wealth and funds, customer geography, expected transactions, counterparties, ownership and the commercial reason for choosing the jurisdiction.
A well-prepared banking application should therefore explain:
- What the company sells.
- Where customers are located.
- Where suppliers are located.
- Which currencies will be received and paid.
- Expected transaction volumes.
- Who owns and controls the business.
- Why Malaysia is relevant to the operating model.
- How funds will move through the company.
The corporate structure, website, contracts, invoices, business plan and expected banking activity should tell a consistent story.
Traditional corporate banking, digital business accounts and multi-currency payment platforms can each have a role. The appropriate combination depends on the company’s transaction corridors, currencies, operating model and financial requirements.
Our guide to opening an offshore bank account in Labuan explains the information that international businesses should prepare before approaching a financial institution.
6. Plan the Family Relocation Alongside the Business
Business migration is rarely only about the founder.
For families moving to Malaysia, practical planning may include:
- Accommodation.
- Schooling.
- Healthcare.
- Dependent immigration arrangements.
- Spouse arrangements.
- Transportation.
- Travel requirements.
- Access to business districts and airports.
Kuala Lumpur provides a broad range of residential areas, international schools, private healthcare and professional services, but the right location depends on the family’s priorities.
A founder who travels frequently may prioritise access to the airport and business districts. A family with school-age children may place greater importance on school location and commuting time.
Family planning should also consider whether a spouse intends to work, establish a business or maintain employment outside Malaysia. The appropriate immigration arrangements can differ depending on the family’s circumstances.
Our family relocation guidance covers the practical considerations that should be reviewed alongside the business move.
7. Organise the First 90 Days Before You Arrive
Business migration is not complete when the company has been incorporated or an immigration pass has been issued.
The first three months are when the legal structure becomes an operating business.
A practical first-90-day agenda can include:
- Finalising corporate documents and governance arrangements.
- Progressing suitable banking and payment applications.
- Establishing accounting and bookkeeping processes.
- Setting up invoicing and payment controls.
- Organising employment, director and service agreements where required.
- Reviewing tax registrations and filing responsibilities.
- Establishing appropriate record-keeping procedures.
Cross-border businesses should maintain contracts, invoices, expense records, board decisions and financial documentation from the beginning.
This is particularly important when the company operates across several jurisdictions. The records should make it possible to understand what the company does, where its decisions are made, how revenue is generated and why funds move between countries.
Why Banking, Immigration and Tax Need to Align
The strongest migration plans are internally consistent.
For example, a company that describes itself as an international consultancy should have contracts, invoices, banking transactions and management arrangements that broadly support that description.
Similarly, if a founder is applying for immigration permission based on a particular business role, the company’s corporate structure and actual activities should support that role.
A mismatch does not necessarily mean the structure is invalid, but it can create additional questions for banks, regulators, immigration authorities or tax advisers.
This is why business migration should be planned as one project rather than as a sequence of unrelated administrative tasks.
Business Migration to Malaysia and ASEAN Expansion
Malaysia can be more than a destination for relocating an existing company. For an appropriate business model, it can become a platform for wider ASEAN expansion.
Before making that decision, consider:
- Which ASEAN markets are the next commercial targets?
- Where are customers and suppliers located?
- Where will employees and contractors work?
- Where will management decisions be made?
- Which licences may be required?
- How will banking and payments operate?
- Which entity will sign regional contracts?
- How will accounting and tax reporting be coordinated?
A founder may eventually need operations in several ASEAN markets. Malaysia can therefore be evaluated as one component of a regional structure rather than as an isolated jurisdiction.
For businesses considering Labuan as part of that strategy, our Labuan Relocation Playbook brings together guidance on company formation, tax, substance, banking, residency and ASEAN expansion.
Common Mistakes in Business Migration to Malaysia
Choosing the cheapest structure first
Price should not be the starting point. A structure that does not support the intended business activity can become more expensive when changes, additional entities or banking problems arise later.
Assuming incorporation solves immigration
Company formation and permission to live or work in Malaysia are separate matters. Immigration planning should be started early.
Applying for banking without a clear business narrative
Banks and payment providers may need to understand ownership, source of funds, customers, suppliers and expected transaction flows. A generic application can create unnecessary questions.
Leaving accounting until the end of the year
International businesses should organise records from the first transaction. Good bookkeeping supports tax compliance, banking reviews, financing and future growth.
Ignoring the founder’s previous country of residence
Relocating to Malaysia does not automatically eliminate obligations elsewhere. Personal and corporate tax positions should be reviewed across the relevant jurisdictions.
Malaysia Should Be Chosen for the Business You Are Building
Malaysia will not be the right operating base for every international entrepreneur.
A company whose entire customer base, workforce and commercial activity remains in Europe may have little reason to establish a Malaysian structure.
Likewise, a business that needs a highly specialised financial ecosystem may require a presence in another regional hub alongside Malaysia.
But for founders building towards ASEAN, Malaysia can offer a combination of regional access, infrastructure, professional services and liveability that deserves to be assessed on its actual merits.
The strongest case is not based on a generic promise that Malaysia is cheaper or easier. It is based on a clear commercial reason for putting part of the business, management or regional strategy there.
How Azean Ventures Approaches Business Migration
Azean Ventures approaches business migration as an integrated implementation exercise.
Depending on the client’s requirements, this can involve company structuring, Labuan planning, business relocation, immigration and residency coordination, banking support, accounting and tax considerations, family relocation and ASEAN expansion planning.
The objective is not to put every founder into the same structure. It is to understand the business first and then coordinate the relevant corporate, financial and personal components around the commercial objective.
Explore our Business Residency & Relocation Services in Malaysia or our Labuan Business Services.
Frequently Asked Questions
What is business migration to Malaysia?
Business migration to Malaysia can involve establishing or relocating business operations while coordinating the company’s corporate structure, immigration position, banking, accounting, tax considerations and practical relocation requirements.
Can a foreign entrepreneur establish a Malaysian company?
Foreign entrepreneurs can establish Malaysian companies, subject to the applicable company, ownership, director, licensing and regulatory requirements. SSM provides the official incorporation framework and requirements.
Does forming a Malaysian company automatically allow the owner to work in Malaysia?
No. Incorporation and immigration permission are separate matters. A founder who intends to work in Malaysia needs to assess the immigration route applicable to the individual’s role and circumstances.
Can Labuan be part of a business migration strategy?
It can be relevant where the company’s activities fall within the applicable Labuan framework and the required regulatory and substance conditions are met. Labuan should not be treated as a generic shortcut for every international business.
Should banking be arranged before moving to Malaysia?
Banking should be considered early because financial institutions may require detailed information about the company’s ownership, activities, source of funds, customers and expected transactions.
Does moving to Malaysia automatically make someone a Malaysian tax resident?
Tax residence depends on the applicable Malaysian rules and the individual’s circumstances. Founders moving from another country should also consider whether they retain tax or reporting obligations elsewhere.
Should family relocation be planned separately from the business?
No. Housing, schooling, healthcare, dependent immigration arrangements and a spouse’s plans can materially affect the practicality of the relocation, so they should be considered alongside the business strategy.
Conclusion
Business migration to Malaysia is best approached as a coordinated commercial decision rather than simply a company-formation exercise.
The corporate structure, immigration route, banking arrangements, tax considerations, accounting systems and family plans should support the same underlying objective.
For founders looking towards ASEAN, Malaysia can form part of a regional operating strategy when there is a genuine commercial reason to establish a presence there.
The most useful first step is to map the existing business, ownership, personal residence position, revenue flows and ASEAN expansion plans together. That makes it easier to determine whether Malaysia should become the main operating base, a regional platform, an operating subsidiary or one component of a wider international structure.
One Response