Labuan Company vs Malaysian Sdn Bhd: Which Structure Fits an International Entrepreneur?
By: Damian Fernandez ©
21st Sept. 2026
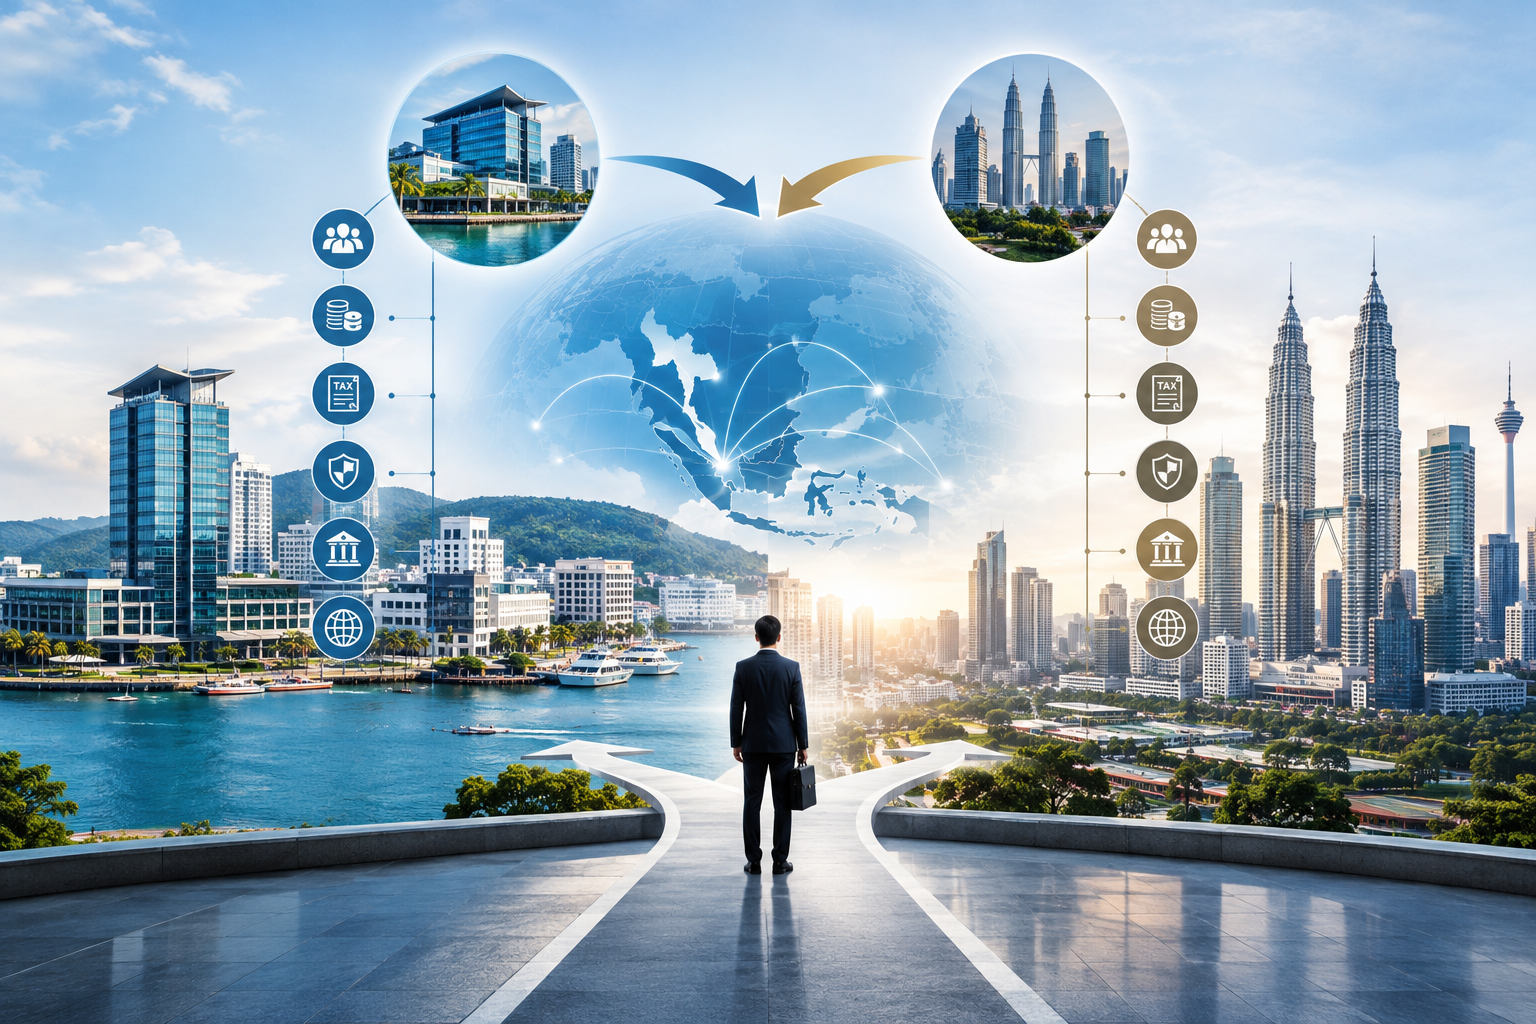
For an international entrepreneur looking at Malaysia, the Labuan company vs Sdn Bhd question is one of the first structural decisions to consider.
Should I establish a Labuan company or an onshore Malaysian Sdn Bhd (a regular private limited company)?
The answer depends less on which company is easier to incorporate and more on what you actually want the business to do.
Both are Malaysian corporate structures, but they operate within different regulatory and tax frameworks and can serve different commercial purposes. Choosing between them therefore starts with understanding where your business will operate, where its customers are located, whether the founders and key personnel intend to live in Malaysia, where operational decisions will be made and how money will flow.
The Malaysian Sdn Bhd: An Onshore Operating Company
A Sdn Bhd is Malaysia’s standard private limited company under the Companies Act 2016. It is generally the natural structure for a business that intends to operate directly in the Malaysian domestic market.
It can employ Malaysian staff, lease premises, contract with Malaysian customers and suppliers, hold local assets and apply for the licences required for regulated activities. A Malaysian private company requires at least one director who ordinarily resides in Malaysia. Companies are also subject to corporate governance, accounting, annual return and financial reporting requirements administered by the Companies Commission of Malaysia (SSM).
For an international company establishing a genuine Malaysian operating presence, the Sdn Bhd can therefore be an appropriate structure.
For current information on Malaysian company incorporation and company requirements, see the official Companies Commission of Malaysia (SSM).
The Labuan Company: Built for Cross-Border Business
A Labuan company operates under the Labuan Companies Act framework and is administered by the Labuan Financial Services Authority (Labuan FSA). It is designed for international business and financial activities conducted in, from or through Labuan.
Labuan companies can be established by residents and non-residents and can undertake permitted international trading, holding, investment and other activities, although certain regulated activities require specific licences.
There is also an important misconception worth clearing up: Labuan is not reserved exclusively for foreigners. Malaysian citizens and Malaysian residents can also establish Labuan companies. The important question is whether the company’s proposed activities and structure fit the Labuan regime.
The distinction is that citizenship, individual residence and the company’s tax position are three different concepts. The structure of the company, its activities, management and control, and the applicable tax rules all need to be considered separately.
This makes Labuan particularly relevant to entrepreneurs whose business is fundamentally international rather than primarily Malaysian.
But there is an important qualification.
Labuan is not simply an offshore version of a Malaysian company. It is a different regime, with its own substance, reporting, tax and regulatory requirements.
For current regulatory information, see the official Labuan FSA information on Labuan companies.
Tax: The Difference That Gets the Most Attention
Tax is inevitably part of the comparison.
Under the Labuan tax framework, a qualifying Labuan trading activity is generally subject to tax at 3% of audited net profits, while qualifying non-trading activity may be subject to a zero rate, provided the applicable requirements are satisfied. A Labuan company may also elect to be taxed under Malaysia’s ordinary Income Tax Act where the relevant provisions allow it.
A Malaysian Sdn Bhd falls under Malaysia’s ordinary corporate income tax regime. The general corporate tax rate is 24%, although qualifying smaller companies may benefit from lower rates on specified bands of taxable income.
But comparing 3% versus 24% and stopping there is a mistake.
The Labuan tax treatment is linked to the nature of the business and compliance with the applicable substance requirements. A business considering Labuan therefore needs to look beyond the headline tax rate and consider its actual activities, management, personnel, operating expenditure and compliance obligations.
The real question is therefore not:
“Which company has the lower tax rate?”
It is:
“Which structure produces the appropriate tax result for the business I am actually operating?”
For a broader look at the costs involved in establishing and maintaining a Labuan company, see our guide to Labuan company incorporation cost.
Substance: Where Labuan Is Different
This is one of the most important distinctions.
A Labuan company seeking the benefits of the Labuan tax framework must meet the substance requirements applicable to its business activity. These can include requirements relating to employees and operating expenditure in Labuan.
That means Labuan should not be approached as a paper company with a registered address while all meaningful activity takes place somewhere else.
The company’s contracts, management decisions, personnel, expenditure and accounting records should make commercial sense when viewed together.
A Sdn Bhd does not operate under this same Labuan economic-substance regime. Its obligations instead arise from the Companies Act, Malaysian tax legislation and whatever licensing and regulatory requirements apply to its particular business.
Businesses considering a Labuan structure should therefore understand the substance requirements before incorporation rather than treating them as an issue to address later.
Banking: Structure Follows the Business
Neither structure automatically guarantees a bank account.
A Labuan company can open accounts with banks in Labuan or elsewhere, subject to the bank’s own due diligence and compliance requirements. In practice, banks will want to understand the company’s ownership, beneficial owners, source of wealth and funds, business model, expected transactions and counterparties.
This is where the choice of entity matters.
A Malaysian Sdn Bhd conducting a genuine Malaysian operation may naturally present a Malaysian banking profile. A Labuan company handling international transactions may require a banking structure that reflects its cross-border business.
The important principle is simple:
Do not choose the company first and try to make the banking fit afterwards.
The business model, company structure and banking plan should be considered together.
Azean Ventures can help clients coordinate these considerations as part of a wider international business structure. Learn more about our Labuan business services.
So Which One Fits?
For some international entrepreneurs, the question is not simply where the company should be incorporated.
It is also:
“How do I establish a legitimate business presence in Malaysia and obtain the appropriate right to live and work here?”
That can materially affect the choice between a Labuan company and a Malaysian Sdn Bhd.
Incorporating or owning a Malaysian Sdn Bhd does not by itself give a foreign individual the right to live and work in Malaysia. Where an entrepreneur intends to work for the company, the company and the proposed position must meet the applicable employment and immigration requirements, including the relevant Employment Pass process where applicable.
The Employment Pass is tied to the employing company and the approved position. The business therefore needs to consider both its corporate structure and its ability to meet the requirements for employing the relevant expatriate.
The requirements have also changed. From 1 June 2026, the minimum salary thresholds for Employment Pass Categories I, II and III were revised to RM20,000, RM10,000 and RM5,000 respectively, with additional conditions applying to the different categories.
Labuan has a separate work-permit framework for expatriates employed by Labuan entities. Labuan FSA has also confirmed that the revised expatriate salary policy applies to Labuan entities from 1 June 2026.
However, this should not be interpreted as meaning that a Labuan company automatically gives its owner Malaysian residence or a work permit.
The practical difference is therefore not simply “Labuan visa versus Sdn Bhd visa.” It is about the relationship between the company, the business activity, the expatriate’s role, the required work authorisation and the intended place of residence.
For entrepreneurs considering the wider relationship between company structure and relocation, see our guide to residency and work permits in Malaysia.
For an international entrepreneur whose primary objective is to establish a genuine Malaysian operating business, a Sdn Bhd may be entirely appropriate.
For an entrepreneur whose business is fundamentally international and who also wants to establish a Malaysian base for themselves and their family, the Labuan framework may warrant closer consideration because the international business structure and Labuan work-permit framework can form part of the same planning exercise.
That makes residence an important factor in the corporate-structuring decision — but not a substitute for meeting the applicable immigration requirements.
In other words, if Malaysian residence is one of the principal objectives, it is worth asking the residence question before deciding which company to incorporate, rather than incorporating first and attempting to solve the immigration question afterwards.
When a Malaysian Sdn Bhd May Be Appropriate
A Malaysian Sdn Bhd may make more commercial sense where the business:
- sells primarily into Malaysia;
- employs substantial Malaysian staff;
- requires Malaysian premises;
- contracts directly with Malaysian customers;
- needs local operating licences; or
- intends to build a substantial Malaysian domestic operation.
When a Labuan Company May Be Worth Considering
A Labuan company may be worth considering where the business:
- generates substantial international revenue;
- conducts approved cross-border trading or services;
- holds international investments or subsidiaries;
- requires an international corporate or investment structure; or
- is being developed as part of a wider Malaysia-and-ASEAN strategy.
The suitability of either structure depends on the company’s actual activities, ownership, management, regulatory requirements and intended markets.
And Sometimes the Answer Is Both
For some international groups, the answer does not have to be Labuan or Sdn Bhd.
An international group may use a Labuan entity for permitted international or holding activities while maintaining a separate Malaysian Sdn Bhd for domestic operations, employees, local contracts or regulated activities.
That can provide a clearer separation between international and Malaysian business activities where the structure reflects genuine commercial activity and is properly documented and maintained.
The Right Question Is Bigger Than “Labuan or Sdn Bhd?”
For an international entrepreneur, the company is only one part of the equation.
Where do you live?
Where are your customers?
Where are your employees?
Where are key management decisions made?
Where will your banking take place?
Where is the intellectual property held?
Where will profits ultimately be taxed?
And, importantly, is Malaysia simply a place to incorporate — or do you intend to build your business and your life here?
The answers to these questions can change the appropriate structure.
At Azean Ventures, we look at Labuan and Malaysia as part of a wider business architecture. The objective is not simply to incorporate a company. It is to create a structure that can support banking, tax compliance, operational substance, Malaysian residence and access to ASEAN markets.
For some businesses, that means a Malaysian Sdn Bhd.
For others, Labuan may provide an appropriate international platform.
And for some, the most suitable structure may involve both.
Our Labuan Relocation Playbook provides further guidance on Labuan company formation, tax, banking, business relocation, residency and ASEAN expansion.
Labuan Company vs Sdn Bhd: Frequently Asked Questions
What is the main difference between a Labuan company and an Sdn Bhd?
A Malaysian Sdn Bhd is generally used for operating businesses in the Malaysian domestic market, while a Labuan company operates within the Labuan regulatory framework and can be used for permitted international business and financial activities. The appropriate structure depends on the company’s actual business model and regulatory requirements.
Is a Labuan company only for foreigners?
No. Labuan companies can be established by residents and non-residents. Nationality alone does not determine whether Labuan is an appropriate structure; the proposed activities and applicable regulatory and tax requirements are more important considerations.
Is Labuan company tax always 3%?
No. The 3% rate applies to qualifying Labuan trading activity subject to the applicable requirements. Qualifying non-trading activities can have different treatment, and a Labuan company may in appropriate circumstances elect to be taxed under Malaysia’s ordinary Income Tax Act.
Does a Labuan company automatically give me Malaysian residency?
No. Incorporating a Labuan company does not automatically grant Malaysian residence or a work permit. Immigration and work-authorisation requirements must be considered separately.
Can a Labuan company open a bank account outside Labuan?
Yes. Labuan FSA states that a Labuan company can open bank accounts with banks in Labuan or outside Labuan, subject to the bank’s own requirements and due diligence.
Can an international entrepreneur use both a Labuan company and an Sdn Bhd?
In some business structures, both entities may have different roles. For example, a group may use a Labuan entity for permitted international or holding activities while a Malaysian Sdn Bhd handles domestic operations. The structure must reflect genuine commercial activities and applicable legal, tax and regulatory requirements.
Which structure is better for ASEAN expansion?
There is no single structure that is appropriate for every ASEAN expansion strategy. The decision depends on where the business operates, where customers and employees are located, the company’s activities, banking requirements, tax considerations, regulatory obligations and the entrepreneur’s broader relocation objectives.
Conclusion
The right structure is the one that matches the business you actually intend to build.
For an international entrepreneur, that decision may include where you and your family intend to live, where the business will operate, how it will be taxed, where management decisions will be made and how banking and compliance will be handled.
Corporate structure, taxation, substance, banking and immigration should therefore be considered as one connected strategy rather than as separate decisions.
If you are comparing a Labuan company vs Sdn Bhd for an international business, Azean Ventures can help you assess the relevant business, structuring, banking, relocation and ASEAN expansion considerations.
Start with the business model. Then choose the structure that fits it.
One Response